Non-governmental organizations (NGOs) play an important role in social development, education, healthcare, poverty reduction, and community welfare. Along with fulfilling their social objectives, NGOs must also maintain financial transparency, proper accounting, and regulatory compliance.
One of the most important parts of NGO financial management is auditing. But many people are unsure about the difference between an internal audit, statutory audit, and FCRA audit.
This guide explains the three types of audits in simple terms and why they matter for NGOs.
An NGO audit is a systematic examination of an organization’s financial records, transactions, accounts, and compliance processes.
Depending on the NGO’s legal structure, activities, funding sources, and applicable laws, different reporting and audit requirements may apply. For charitable or religious trusts and institutions, the Income Tax Department also specifies circumstances in which audit reports such as Form 10B or Form 10BB are applicable.
An effective audit helps an NGO:
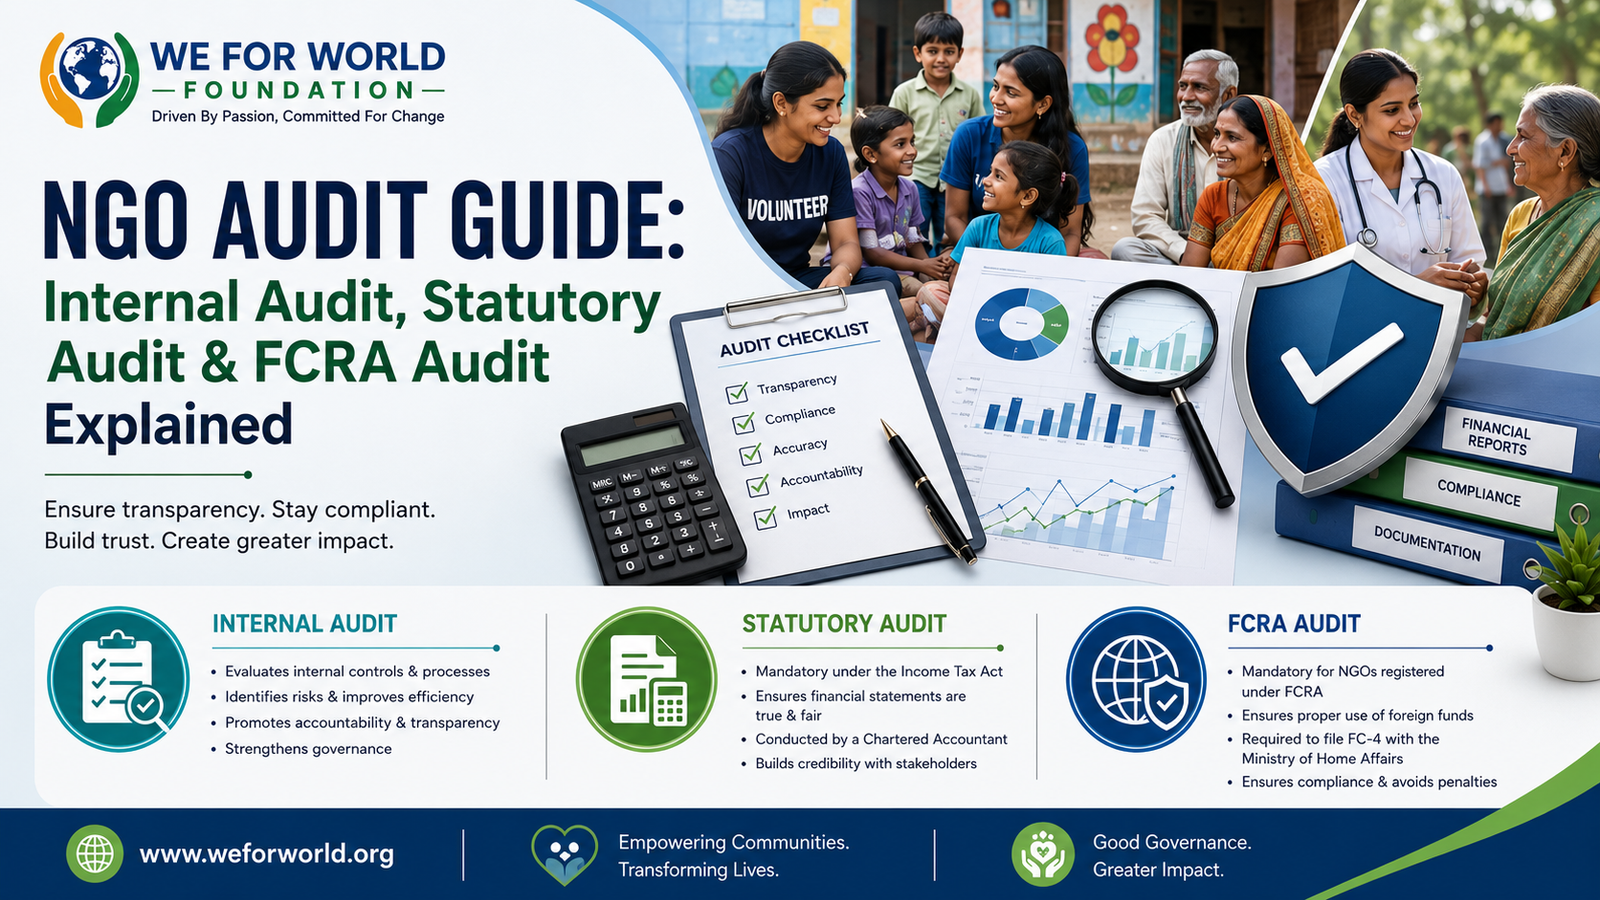
An internal audit focuses primarily on the NGO’s internal systems, controls, processes, and financial management.
Unlike a statutory audit, an internal audit is generally performed to help management identify weaknesses and improve the organization’s operations.
An internal audit may review:
The objective is not simply to find mistakes. It is to identify potential risks and recommend improvements before they become larger problems.
A statutory audit is an audit required under the applicable law or legal framework governing the organization.
The exact requirements can depend on whether the NGO operates as a trust, society, Section 8 company, or another legal entity, as well as its activities and applicable tax provisions.
For eligible charitable or religious organizations, the Income Tax Department currently provides for audit reporting through Form 10B or Form 10BB, depending on the circumstances. For example, Form 10B can apply where the specified conditions include total income exceeding ₹5 crore, receipt of foreign contribution, or use of income outside India.
A statutory audit generally involves examining the NGO’s:
The auditor then provides the relevant audit report or certification as required.
NGOs that receive foreign contributions must pay particular attention to compliance under the Foreign Contribution (Regulation) Act, 2010 (FCRA).
FCRA compliance involves maintaining appropriate records of foreign contributions received and how those funds are utilized.
An NGO receiving foreign contribution is required to file its annual return in Form FC-4 online. According to the Ministry of Home Affairs’ FCRA guidance, the annual return is filed for each financial year within nine months from the end of the financial year, i.e. by 31 December, and is accompanied by the relevant balance sheet and receipt-and-payment statement certified by a Chartered Accountant. A NIL return is also required where applicable.
An FCRA-focused review may examine:
The current Form FC-4 itself captures details relating to foreign contribution receipts, donors, purposes, utilization, and related financial information.
| Type of Audit | Main Purpose | Focus |
|---|---|---|
| Internal Audit | Improve systems and controls | Internal processes, risks and financial controls |
| Statutory Audit | Meet applicable legal requirements | Financial statements and statutory compliance |
| FCRA Audit | Support FCRA compliance | Foreign contribution receipts and utilization |
Although these audits have different objectives, they complement each other. A well-managed NGO should maintain strong accounting and documentation throughout the year rather than preparing records only when an audit is approaching.
Audit is not merely a compliance exercise. It can help an NGO demonstrate that funds are being managed responsibly.
A properly maintained audit trail can provide confidence to:
Good financial transparency can also strengthen an NGO’s reputation and make it easier to demonstrate responsible use of funds.
Some common issues that can create problems during an NGO audit include:
Regular financial reviews can help identify these issues early.
NGOs can make the audit process smoother by maintaining records throughout the year.
A basic audit-preparation checklist should include:
Internal audit, statutory audit, and FCRA audit serve different purposes, but all contribute to better financial governance and transparency.
For NGOs, maintaining accurate records throughout the year is far better than trying to organize everything at the end of the financial year. Strong accounting practices, effective internal controls, and timely compliance can help an organization protect its reputation and focus more effectively on its social mission.
If an NGO receives foreign contributions, FCRA compliance deserves additional attention because the applicable rules require specific reporting and documentation. The Ministry of Home Affairs provides the official FCRA portal and related guidance for registered associations.
Disclaimer: NGO audit and compliance requirements can vary depending on the organization’s legal structure, registrations, activities, funding sources, and applicable laws. This article is intended for general awareness and should not be treated as legal, tax, or professional advice.